
Most families don’t think about a power of attorney until they suddenly need one. Dad falls, ends up at Houston Methodist, and by the time the discharge planner starts asking questions, the family discovers that no one has legal authority to act on his behalf. The bank won’t discuss his accounts with his daughter, the doctor’s office can’t release certain record, and siblings may disagree about what should happen next.
A power of attorney (POA) can help prevent that kind of crisis. It allows an older adult to legally designate someone they trust to handle specific financial, legal, or health care matters if they are unable to do so themselves. Setting one up while your parent is still able to make and communicate decisions is generally much easier than trying to sort it out during an emergency.
Texas law recognizes several types of powers of attorney, and the authority granted by each one can be very different. Understanding those differences can help families choose the right arrangement and avoid assuming that one document covers everything.
In this guide, we’ll explain what a power of attorney is, the five types seniors and their families may encounter, what each one covers under Texas law, and when it makes sense to set one up. We’ll also cover an important practical question that many POA guides overlook: what a home care agency may need from you before care begins when you are helping manage an aging parent’s care.
This article is general information, not legal advice. Talk to a Texas elder law attorney about your family’s situation.
Key Takeaways
- A power of attorney allows an older adult to choose someone they trust to handle certain financial, legal, or medical decisions on their behalf.
- Texas families may encounter durable, medical, financial, springing, and limited powers of attorney, and the authority provided by each can differ.
- Planning ahead matters because a parent generally must have the mental capacity to understand the document when it is signed.
- A power of attorney and guardianship are not the same. A POA is created voluntarily in advance, while guardianship involves a court process after someone can no longer manage their affairs.
- If you are coordinating home care for an aging parent, having the appropriate POA documents available can help clarify who is authorized to sign agreements, approve care changes, handle payments, and communicate during an emergency.
- Families in River Oaks and Houston’s Inner Loop can address legal planning and home care planning before a hospital discharge or other crisis makes decisions more urgent.
What Is a Power of Attorney (POA) for Seniors?
A power of attorney is a signed legal document that lets a senior choose a trusted person to handle financial, legal, or medical decisions on their behalf, either now or if they later lose the ability to decide for themselves.
It is important to understand what these terms mean when it comes to power of attorney:
- Principal: The senior who creates the POA and grants the authority.
- Agent: The person chosen to act for the principal.
- Attorney-in-fact: An older name for the agent. Texas law uses both terms, and the agent does not need to be a lawyer.
A few important limits can surprise families. First, a power of attorney ends when the principal dies. Under the Texas Estates Code, the agent’s authority stops at death. From that point forward, the executor named in the will, or a court-appointed administrator if there is no executor, handles the estate. Second, a POA does not replace a will. A power of attorney governs decisions made during your parent’s lifetime; a will determines what happens to their property after death. For most seniors, these documents serve different purposes and both may be important.
In Texas, financial powers of attorney are governed by the Durable Power of Attorney Act in Estates Code Chapters 751 and 752, which the Legislature substantially revised in 2017. Medical powers of attorney are governed separately under the Texas Health and Safety Code. That distinction matters because the documents grant different types of authority.
Despite the importance of advance planning, many Americans still do not have these documents in place. A review of 150 studies involving 795,909 people found that only 36.7% of U.S. adults had completed any advance directive, including just 29.3% who had completed a living will (Health Affairs, via PubMed). Older adults are somewhat more likely to have completed advance planning documents, but the numbers remain surprisingly low. The University of Michigan’s National Poll on Healthy Aging found that 46% of adults ages 50 to 80 had completed at least one advance care planning document, while only 37% had both a medical durable power of attorney and an advance directive (University of Michigan IHPI).
What Are the 5 Types of Power of Attorney for Seniors?
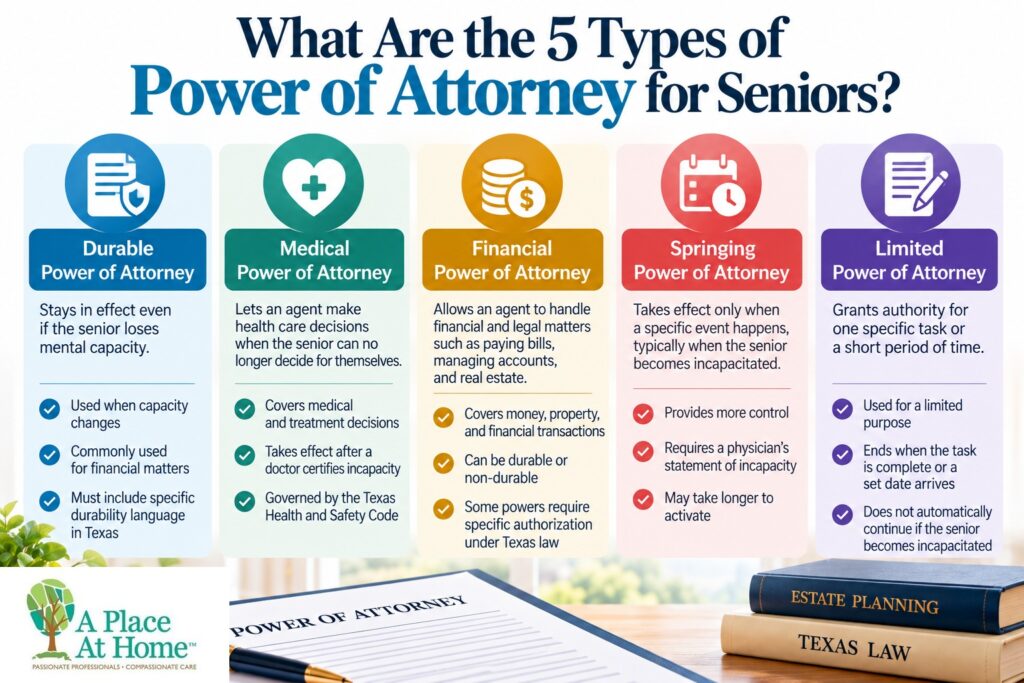
The five types of power of attorney seniors and their families commonly encounter are durable, medical, financial, springing, and limited. These categories are not always mutually exclusive. In Texas, for example, a financial power of attorney can be durable, meaning it remains effective if the principal becomes incapacitated, and springing, meaning it takes effect only when a specified condition is met.
Understanding how these terms overlap is important because they describe different aspects of the authority being granted, not necessarily five separate documents.
What is a durable power of attorney?
A durable power of attorney stays in effect after the principal loses mental capacity, which is exactly when families need it most. A non-durable POA ends the moment the principal becomes incapacitated.
Texas does not presume durability. Under Texas Estates Code § 751.0021, the document must include language such as “This power of attorney is not affected by subsequent disability or incapacity of the principal,” or similar wording. It must also be signed by the principal and acknowledged before a notary. Texas does not require witnesses for a durable financial POA.
What is a healthcare power of attorney?
In Texas, a healthcare power of attorney is called a medical power of attorney, and it lets an agent make medical decisions only after the principal’s attending physician certifies in writing that the principal can no longer make them.
It’s governed by Chapter 166 of the Texas Health and Safety Code, not the Estates Code. The agent can consent to, refuse, or withdraw treatment, including life-sustaining treatment. Texas law draws a few hard lines: the agent cannot consent to voluntary inpatient mental health services, convulsive treatment, psychosurgery, abortion, or neglect of comfort care (Texas Medical Association).
To sign one, your parents can either have it notarized or sign in front of two adult witnesses. At least one witness cannot be a relative, an heir, the agent, or someone involved in their care.
What is a financial power of attorney?
A financial power of attorney lets the agent handle money and property such as paying bills, managing bank and investment accounts, filing taxes, dealing with Social Security and insurance, and selling or managing real estate.
Texas offers a fill-in-the-blank Statutory Durable Power of Attorney form (Estates Code § 752.051), where the principal initials each category of authority they want to grant. Some powers, like making gifts or changing beneficiary designations, require specific, separate authorization. If the agent will sell or mortgage your parent’s home, Texas requires the POA to be recorded with the county clerk (in Harris County, that’s the Harris County Clerk’s office).
What is a springing power of attorney?
A springing power of attorney takes effect only when a specific event happens, usually the principal’s incapacity, rather than on the day it’s signed.
Texas allows springing durable POAs; the statutory language is “This power of attorney becomes effective on the disability or incapacity of the principal.” The appeal is control: your parents keep full authority until they truly can’t manage. The drawback is delay. Before the agent can act, they usually need a physician’s written statement of incapacity, and a bank may take days to review it. Many Texas elder law attorneys recommend an immediately effective durable POA with a trustworthy agent instead.
Note that a Texas medical POA already works this way by default: the agent can’t act until a doctor certifies incapacity.
What is a limited power of attorney?
A limited (or special) power of attorney grants authority for one specific task or a short period, such as closing on the sale of a house or managing a single account while the principal is traveling or recovering from surgery.
It ends when the task is done or the stated date arrives. Unless it includes durability language, it also ends if the principal becomes incapacitated, so it’s a poor substitute for a durable POA in long-term planning.
What’s the Difference Between Power of Attorney and Guardianship?
A power of attorney is voluntary and preventive: your parents choose someone they trust to act on their behalf while they still have the legal capacity to make that decision. Guardianship is different. It is a court-ordered process that may become necessary after a person can no longer manage their affairs or make informed decisions for themselves. Instead of choosing an agent in advance, the court determines who will have authority to act for them.
Texas treats guardianship as a last resort. Since 2015, a Texas probate court must find by clear and convincing evidence that less restrictive alternatives, including a durable power of attorney and medical power of attorney, have been considered and are not feasible before appointing a guardian. In practical terms, putting the right POA documents in place while your parents still have capacity can help avoid the need for a court-appointed guardian altogether.
| Power of attorney | Guardianship | |
|---|---|---|
| Who decides | Your parents choose their own agent | A probate judge appoints the guardian |
| When it’s created | While your parent still has capacity | After your parent has lost capacity |
| Process | Private document, signed and notarized | Court application, physician’s exam, court-appointed attorney ad litem, hearing |
| Typical cost | A few hundred to a couple thousand dollars for attorney drafting | Often $3,000 to $10,000 uncontested; more if contested |
| Timeline | Days to a few weeks | Weeks to months |
| Ongoing oversight | None by default; you can build in accounting requirements | Court supervision, annual reports, possible bond |
| Your parent’s rights | Keeps all rights; can revoke while competent | May lose the right to make their own decisions |
| Privacy | Private | Public court record |
In the state of Texas, if a court later appoints a permanent guardian of your parent’s estate, the agent’s authority under a durable POA ends. The two don’t run side by side.
Planning Ahead for a Loved One in River Oaks?
If you are already thinking about who will handle decisions for an aging parent, it may also be a good time to talk about what support they would want at home if their needs change. For busy adult children in River Oaks, West University, Upper Kirby, Montrose, and nearby Houston Inner Loop communities, planning before a hospital stay or sudden decline can make the transition to care much easier.
Call A Place At Home – River Oaks at (346) 590-6071 to schedule a free consultation and discuss what an in-home care plan could look like for your loved one.
When Should a Senior Set Up a Power of Attorney?
A senior should set up a power of attorney before a diagnosis, not after, because the document is only valid if your parent has the mental capacity to understand what they’re signing.
That window can close faster than families expect. A stroke, a fall with a head injury, or a quick decline in Alzheimer’s disease can take away capacity in days. Once it’s gone, a POA is no longer an option, and guardianship is what’s left.
In a University of Michigan poll, among adults 50 to 80 who hadn’t completed a medical POA or advance directive, 62% said they simply hadn’t gotten around to it, and 15% said they didn’t know how (University of Michigan IHPI). Procrastination, not disagreement, is the main reason families end up unprepared.
Good moments to start the conversation include:
- Retirement, or turning 65 and enrolling in Medicare
- The death or illness of a spouse, especially if that spouse was the named agent
- Early signs of memory changes, before a formal diagnosis
- A scheduled surgery or hospital stay
- A move to a new state, or a move closer to family in Houston
- The first conversation about bringing in home care
If your parents already have a POA, check the date. Texas updated its statutory durable POA form in 2017 and its medical POA form after that. Older documents may still be valid, but an outdated or out-of-state form is more likely to draw questions from a bank.
What Happens if a Senior Needs Care and Has No Power of Attorney?
If a senior needs care and has no power of attorney, no one has clear legal authority to manage their money or make most decisions for them, and the family usually ends up asking a court to appoint a guardian.
Here’s how it typically unfolds:
- The bank freezes access: You can’t pay Mom’s property taxes, her mortgage, or her caregivers from her accounts. Being her child or even being added to her account as an “authorized user,” isn’t the same as legal authority. Texas has no default rule that lets family members manage an incapacitated adult’s finances.
- Providers limit what they share: Under HIPAA, doctors and hospitals can talk with family members involved in a patient’s care, but they generally won’t release full medical records or accept your instructions without legal authority. Texas does have a default surrogate law (Health and Safety Code Chapter 313) that lets a spouse, then adult children, then parents consent to some medical treatment in a hospital, nursing home, or licensed home health setting. It doesn’t cover finances, housing, or the care contract, and it has its own limits.
- Siblings disagree, and nobody breaks the tie: One sibling wants Dad home with 24-hour care. Another wants assisted living. A third lives in Dallas and doesn’t trust either of them. Under Texas’s surrogate statute, disputes over who gets to decide go to court. Without a named agent, there’s no tiebreaker.
- The family files for guardianship: Someone applies in Harris County Probate Court. The process includes a physician’s certificate of medical examination, a court-appointed attorney ad litem for your parents, notice to family members, and a hearing.
The cost adds up quickly. An uncontested adult guardianship generally costs $3,000 to $10,000, and contested cases can exceed $20,000. The timeline runs weeks to months, and care decisions sit frozen while you wait. Temporary emergency guardianships exist in Texas, but they’re short-term and add their own legal fees.
Then the expenses continue in the form of annual reports to the court, accountings, and in many cases a bond. A power of attorney, signed early, avoids nearly all of it.
Who Should You Name as Power of Attorney for an Elderly Parent?
You should name the person your parents trust most to follow their wishes, handle money honestly, and stay organized under pressure, which is not always the oldest child or the one who lives closest.
A strong agent:
- Is trustworthy with money and has a stable financial life of their own
- Knows your parent’s values, including their religious and moral beliefs, which Texas law requires a medical agent to consider
- Is organized enough to keep receipts and records (Texas agents have a legal duty to keep records and account for transactions)
- Lives close enough to deal with banks, doctors, and the home care team, or can manage it reliably from a distance
- Gets along with siblings well enough to keep everyone informed
- Is willing to serve, has said yes, and understands what the job involves
Common disqualifiers:
- Serious debt, gambling problems, or substance misuse
- A history of borrowing money from your parents that wasn’t repaid
- Open conflict with siblings or other family members
- Anyone pressuring your parents to name them or to change their documents
- Your parent’s doctor or paid caregiver. Under Texas law, a health or residential care provider (or their employee, unless a relative) can’t serve as medical agent while also providing care.
Practical safeguards to ask your attorney about:
- Name a successor agent: If your first choice dies, becomes ill, or resigns, the successor steps in without a trip to court. Texas allows successor agents in both financial and medical POAs.
- Require annual accounting to a second family member: Texas already gives the principal the right to demand an accounting. You can go further and require the agent to share statements with a sibling or another trusted person every year.
- Split financial and healthcare authority when it makes sense: The sibling who’s great with spreadsheets might not be the one who should talk to the ICU team. In Texas, these are separate documents anyway, so naming different agents is simple.
- Limit gifting: Texas requires gift and beneficiary-change powers to be granted specifically. If your parents don’t want an agent moving money to family, leave those powers out or cap them.
How Do You Get a Power of Attorney for an Elderly Parent?
You get a power of attorney for an elderly parent by having your parent, while they still have capacity, sign a properly drafted document that meets Texas execution rules. You can’t sign it for them, and you can’t get one on their behalf once capacity is gone.
- Confirm capacity: Your parents must understand what the document does and who they’re giving authority to. If there’s any memory concern, ask their physician for a brief capacity note dated close to the signing. It helps if anyone challenges the document later.
- Choose the agent and a successor: Have the conversation with your parent first, then with the people being named. Both should agree to serve.
- Define the powers granted: Decide which financial powers to include (banking, real estate, taxes, retirement accounts, gifting) and whether the POA takes effect now or springs on incapacity. For the medical POA, note any treatment limits or wishes.
- Have a Texas elder law attorney draft it: Texas provides statutory forms, but an attorney can tailor them, coordinate them with your parent’s will or trust, and add safeguards like accounting requirements. Downloaded templates are frequently questioned or rejected by banks and brokerages, especially if they’re missing Texas durability language, use another state’s form, or are improperly notarized. Requirements differ by state, so a form that works in Florida or California may cause problems in Houston.
- Execute it according to Texas rules: A durable financial POA must be signed and acknowledged before a notary. A medical POA must be either notarized or signed in front of two qualified adult witnesses. If the agent may need to sell or mortgage real estate, record the financial POA with the county clerk.
- Distribute copies: Give copies to your parent’s bank and investment firms, their primary physician and any specialists, the hospital they’re most likely to use, and the home care agency. Keep the original somewhere the agent can reach quickly, not in a safe-deposit box only your parents can open.
Banks and other institutions presented with a valid Texas durable POA generally must accept it, or request an agent’s certification or an attorney’s opinion within 10 business days (Texas Estates Code § 751.201). That protection works best when the document is drafted correctly in the first place.
Coordinating Care From a Distance?
If you have a loved one in River Oaks or Houston’s Inner Loop but spend much of your day at work, travel frequently, or live outside Houston, getting the right documents and care contacts organized ahead of time can make it easier to respond when needs change. A Place At Home – River Oaks can help your family plan the practical side of in-home support while your attorney handles the legal documents.
Call (346) 590-6071 for a free home care consultation before a hospital discharge or care need becomes urgent.
Does a Home Care Agency Need a Copy of the Power of Attorney?
Yes. A home care agency needs a copy of the power of attorney because it tells the agency who has legal authority to sign for your parents, approve changes to their care, pay for services, and make decisions in an emergency.
Here’s what the agency uses it for:
- Signing the service agreement: If your parent can sign for themselves, they should. If they can’t, the agency needs to know the person signing has authority under a financial POA.
- Authorizing care plan changes: When needs shift, such as moving from a few hours of companion care to overnight or 24-hour care, someone has to approve it. The POA shows who that is, so caregivers aren’t caught between siblings giving different instructions.
- Receiving billing: Invoices, long-term care insurance claims, and payment authorizations go to the financial agent.
- Emergency contact and decisions: If your parent falls or becomes confused during a shift, the agency calls 911 first, then the person with authority. A medical POA tells the care team who can speak with doctors once a physician certifies your parent can’t decide for themselves.
Give the agency copies of both the financial and medical POAs, plus any directive to physicians or out-of-hospital DNR order, at the start of care. If documents change, send the updated versions. A good agency will ask for these during intake but bringing them yourself speeds things up.
At A Place At Home – River Oaks, we review this documentation during the first consultation so families know exactly what’s in place before a caregiver ever arrives. It matters for every service we offer, from personal and companion care to Alzheimer’s and dementia care and 24-hour and live-in care.
Get Your Paperwork and Your Care Plan in Order Together
A power of attorney is one of the simplest and least expensive ways to prepare for the possibility that your parents may eventually need someone else to act on their behalf. But it only works if your parents put it in place while they still have the capacity to make that decision. Choosing a trustworthy primary agent and backup, using Texas-compliant documents prepared with guidance from an elder law attorney, and making sure the right people have copies can prevent confusion when a crisis occurs.
If home care may be part of the plan, it also helps to address the practical details before care is needed. A Place At Home – River Oaks offers in-home care that starts with a free consultation for families in River Oaks and Houston’s West and Southwest Inner Loop. During the visit, our care coordinators can assess your parent’s needs, discuss the type of support that may be appropriate, and explain what documentation we’ll need before services begin, including who will sign the service agreement and who we should contact in an emergency.
Taking care of those details ahead of time means your family is less likely to discover a missing signature, unclear authority, or other paperwork issue when your parent needs help most.
Plan the Care Before Your Family Needs It
For adult children managing demanding careers, travel, their own households, and an aging loved one’s needs, waiting for the next fall, hospital stay, or memory-related concern can make an already difficult situation more stressful. A Place At Home – River Oaks can help you put a personalized home care plan in place for a loved one in River Oaks, West University, Upper Kirby, Montrose, Highland Village, Afton Oaks, and nearby Houston Inner Loop communities.
Call (346) 590-6071 to schedule your free consultation and talk through the level of support your loved one may need now and how care can adapt in the future.
Frequently Asked Questions About Power of Attorney for Seniors
Can a power of attorney be revoked?
Yes. A senior with capacity can revoke a Texas durable financial POA at any time, ideally in writing, with notice to the agent and to every bank or institution that has a copy. If the POA was recorded with the county clerk, the revocation should be recorded too. A Texas medical POA is even easier to revoke: your parents can do it orally or in writing by telling the agent or their doctor, and Texas allows this regardless of their capacity. Signing a new medical POA automatically revokes the old one.
Can someone with dementia sign a power of attorney?
Sometimes. A dementia diagnosis doesn’t automatically disqualify someone. What matters is whether they understand the document and its consequences at the moment they sign. Many people in the early stages of Alzheimer’s or other dementias still have that capacity. Once the disease progresses, they may not, and the family may need guardianship instead. If there’s any doubt, ask the physician to document capacity close to the signing date.
Does a power of attorney cover nursing home or home care decisions?
Usually, yes, but it takes both documents. The financial POA lets the agent sign contracts and pay for home care, assisted living, or a nursing home. The medical POA lets the agent make health care decisions once a doctor certifies your parent can’t. Where your parent lives can fall in a gray area between the two, so ask your attorney to address residence and care-setting decisions explicitly. Texas law also says an agent can’t force treatment over your parent’s objection.
Is a power of attorney valid in another state?
Generally, yes. Texas recognizes a durable POA signed in another state if it was valid under that state’s law, and most states extend the same courtesy to Texas documents. In practice, out-of-state forms can slow things down at the bank. If your parents move to Houston from another state, have a Texas attorney review their documents and consider signing new Texas versions.
What is the difference between a power of attorney and a living will?
A power of attorney names a person to make decisions for your parents. A living will, called a Directive to Physicians in Texas, records your parent’s own instructions about life-sustaining treatment if they have a terminal or irreversible condition. The medical POA is broader: it covers nearly all health care decisions, not just end-of-life ones. Most seniors should have both, along with a durable financial POA and a will.